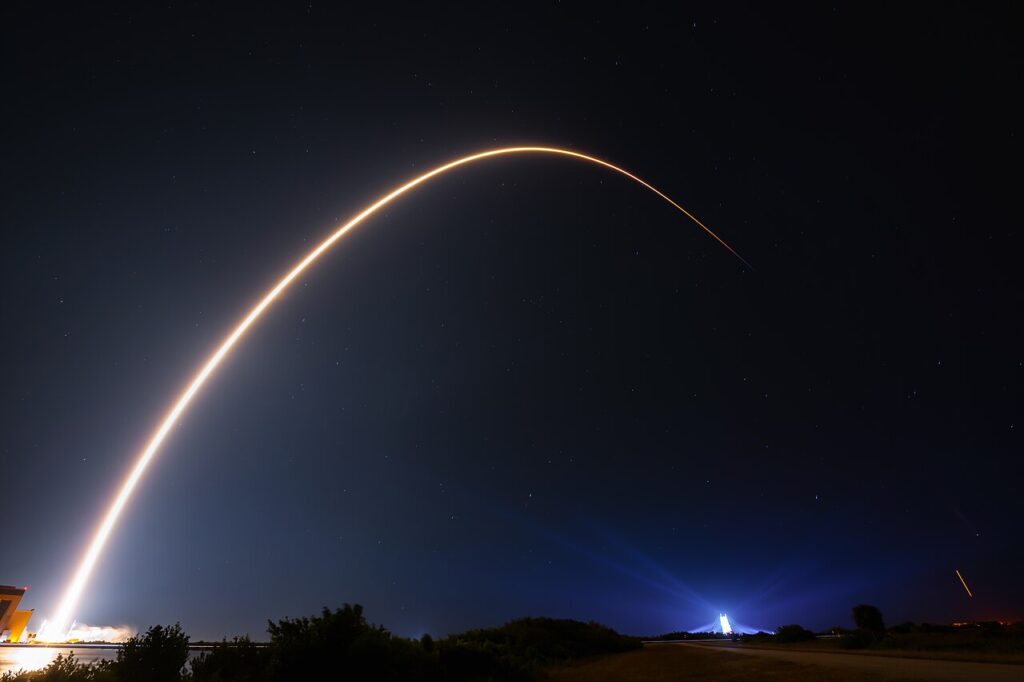
Elon Musk announced on Sunday, in a post on X, that SpaceX has closed $40 billion in debt financing to buy graphics processing units — the chips that power artificial intelligence — and then used the same post to deliver a warning to an entire industry. The debt markets, he wrote, “have almost entirely shut off access to money for any company that doesn’t have substantial revenue independent of AI data centers”. SpaceX, he said, got its deal done because “we’re investment grade and have Starlink & launch revenue”. The rest, in his phrase, face “guppy-level death and consolidation”.
The structure of the deal matters as much as its size. Reports of the package, which had circulated since early October, describe roughly $10 billion in bank loans plus $30 billion in investment-grade bonds, arranged through a special-purpose vehicle that keeps the debt off SpaceX’s own balance sheet. The money is primarily callable debt — repayable early at SpaceX’s option — for GPU purchases arriving in the first and second quarters of 2027. Musk added that it is “not a major factor this quarter”, and that SpaceX expects $35 billion to $40 billion in capital expenditure in the fourth quarter alone, according to chief financial officer Bret Johnsen.
That last figure is the context the $40 billion needs. SpaceX completed an $86 billion initial public offering in June 2026 and raised a further $25 billion in bonds soon after. The chips are destined for AI data centres built on Nvidia hardware, including the Colossus cluster in Memphis — the same build-out that has made SpaceX, a rocket company, into one of the AI industry’s biggest buyers of compute.
So what is a “neocloud”, and why does Musk think more than 200 of them are in trouble? The word describes the new breed of cloud firms — CoreWeave and Nebius are the best known — that do one thing: buy Nvidia GPUs, mostly with borrowed money, and rent the computing power to AI companies. Unlike Amazon, Microsoft or Google, they sell almost nothing else. Their business is the spread between what the GPUs earn in rent and what they cost to buy, power and finance.
That model works while credit is cheap and GPU prices hold. It breaks when lenders start asking harder questions — about how fast the chips lose value (a top-line GPU stays top of the line for roughly three to four years), about customer concentration (Microsoft alone accounted for about two-thirds of CoreWeave’s 2025 revenue, according to company filings cited by Reuters), and about whether the AI labs renting the capacity will keep paying today’s prices. In the week before Musk’s post, shares of CoreWeave, Nebius and IREN each fell roughly 11–12% in a single session as credit markets repriced their debt.
Musk’s post is, in part, self-interested theatre: a man who just borrowed $40 billion telling the market that borrowing has become nearly impossible for everyone else. But the underlying split he describes is real, and it is the story of the AI boom’s second phase. On one side sit companies with recurring revenue from somewhere other than AI — Starlink subscriptions, rocket launches, search ads, software — that can borrow at investment-grade rates. On the other sit companies whose only revenue is AI itself, borrowing against chips that depreciate and contracts that can be renegotiated. The first group can keep building through a credit squeeze. The second has to survive it.
Whether “guppy-level death” arrives is a prediction, not a fact, and Musk has made confident predictions about other people’s industries before. What is verifiable is narrower: SpaceX has the money, the chips arrive next year, and the lenders who funded this deal did so on the strength of Starlink and launches — not on AI alone. For the 200-plus firms without that cushion, the next few quarters will be the test. Related coverage: Tesla’s flying Roadster stunt, Amazon’s 1,000th Leo satellite, and why AI’s godfathers can’t agree on how dangerous AI is.

One Comment