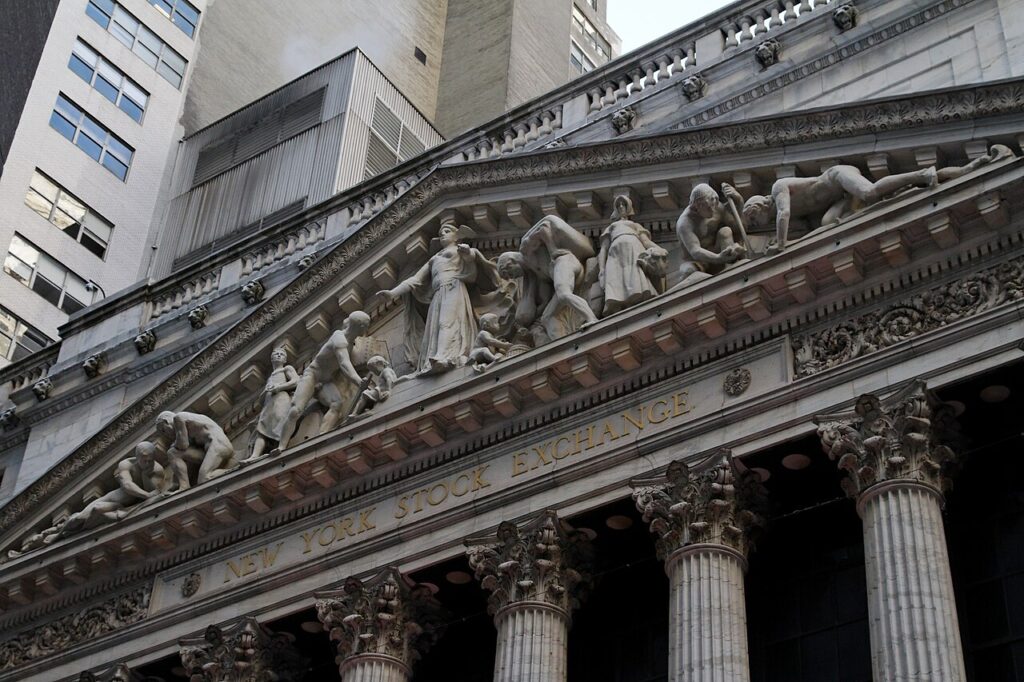
Informopedia Explains: On Friday morning, Jakarta’s stock market fell 8% within minutes of opening — not because of anything Indonesian companies had done overnight, but because of a consultation paper published in New York. This is the story of the index that can sink a market with a memo.
The memo that sank a market
MSCI, the index company whose classifications decide which countries’ stocks the world’s passive investment funds are allowed to hold, launched a consultation on October 15 on moving Indonesia from emerging-market to standalone-market status. By Friday’s open, the Jakarta Composite Index had collapsed 8%, triggering an automatic 30-minute trading halt, and ended the session down around 11% — the worst day since early 1998. The rupiah slid to about 18,035 per dollar, near its all-time low.
None of this was about Indonesian earnings. It was about a list. To understand why a list can do that, you have to understand what MSCI is — and why its lists are the closest thing global finance has to law.
What MSCI actually is
MSCI — originally Morgan Stanley Capital International — is an index provider. It does not buy or sell stocks. It publishes the benchmarks that trillions of dollars in investment funds measure themselves against: the MSCI Emerging Markets Index, the MSCI World Index, and dozens of country and sector variants. If your pension fund owns “emerging market equities,” there is a good chance it owns them in exactly the proportions MSCI dictates.
That gives MSCI a peculiar kind of power. Inclusion in an index is not a prize; it is plumbing. But exclusion is a punishment with mechanical force: funds that track the index must sell, whether or not they believe in the country. MSCI’s classifications are reviewed in a formal, almost judicial process — annual Market Classification Reviews, consultations, feedback periods — and the criteria are about market accessibility and integrity: can foreign investors get in and out, is trading fair, is ownership transparent, is the currency convertible.
How a country gets in — or thrown out
A country does not get ejected for being poor. Frontier markets like Vietnam or Nigeria sit in MSCI’s indexes despite far smaller economies than Indonesia’s. Ejection is about the rules of the game, not the size of the prize.
In Indonesia’s case, MSCI’s complaint was specific: “persistent opacity in shareholding structures and suspected coordinated trading behavior.” Translation: investors could not see who really owned what, and trading patterns suggested insiders were moving prices in concert. The timeline tells the story of patience exhausted. In January 2026, MSCI issued a warning after a partial market freeze, sparking a historic rout. In June, it flagged the opacity problem and said a consultation would follow if progress was not evident by the November review. Jakarta announced reforms — disclosure of shareholders above 1%, a published list of stocks with concentrated ownership, a roadmap to a 15% minimum free-float requirement. On October 15, MSCI’s verdict: “Despite the announced reforms, significant concerns remain around market dysfunction, including continued suspected coordinated trading behaviour and lack of evidence of meaningful enforcement.”
Note the skipped step. MSCI did not propose downgrading Indonesia to frontier status — it proposed skipping frontier entirely for “standalone” status, explaining that “a reclassification to Frontier Markets would not properly recognize the depth of the market problems.” That is the index equivalent of failing a student so badly you invent a new grade.
Why ejection moves billions
Here is the mechanics. A large share of global equity money is passive: index funds and ETFs that own whatever the index owns, in the index’s weights. When a country leaves an index, those funds must sell — not because they have lost faith, but because their mandate says so. Active managers benchmarked against the index face the same pressure: holding a country that is no longer in your benchmark is a career risk.
MSCI also froze Indonesia’s index while the consultation runs: no increases to foreign inclusion factors, no new additions, no upward migrations between size segments, and deletions for concentration-flagged stocks. The freeze means the index can only shrink, never grow, until the decision lands. That is why Friday’s 11% plunge was not an overreaction to a maybe — it was the market pricing in the forced selling of a certainty, discounted for the small chance Jakarta fixes this in time.
The lonely club
If the reclassification goes through, Indonesia would join one of the smallest clubs in finance: the standalone markets. The current members are Argentina, Lebanon, and Palestine. Indonesia would be the first Asian member — and the largest economy ever to hold the title.
That contrast is the point. Standalone status is not really about economic development; Argentina has a sophisticated financial system and Lebanon was once a banking hub. It is about trust in the market’s machinery. A country can have skyscrapers, a trillion-dollar economy, and the world’s fourth-largest population, and still be told its stock market is not a place where outsiders’ money is safe.
What happens next for Indonesia
The process now runs on rails. MSCI is taking client feedback until April 30, 2027, and will announce its decision on or before June 30, 2027. It has said it “expects to proceed with the proposed reclassification unless the consultation identifies clear evidence of material improvements in market governance and functioning.” The burden of proof has flipped: Jakarta must now prove, with evidence, that trading is clean and enforcement is real.
The Indonesia Stock Exchange says it will seek clarification on MSCI’s rationale and criteria, insisting on “significant progress and reform measures.” One small comfort for Jakarta: rival index provider FTSE Russell recently reaffirmed Indonesia as an emerging market, so not every gatekeeper agrees. But MSCI is the benchmark that matters most, and its consultation is the one moving prices.
For President Prabowo Subianto, the stakes are personal as well as national. He has made attracting foreign capital the centerpiece of his economic agenda for Southeast Asia’s largest economy. An ejection would make that pitch measurably harder — every roadshow abroad would begin with the same question.
Why this matters beyond Indonesia
Index power is one of the least democratic forces in global finance. No one elects MSCI; no parliament votes on its consultations. Yet its classifications move more money than most governments’ budgets, and its verdicts are delivered in the bloodless language of methodology papers. Indonesia’s ordeal is a reminder that in modern markets, the most consequential decisions are often not made by traders, or even by central banks, but by the people who write the lists.
Read today’s full story: MSCI’s consultation on moving Indonesia to standalone status — and, for the wider economic weather, the IMF’s warning that the global economy’s cushion is thinning. The full MSCI’s consultation documents are public.

One Comment