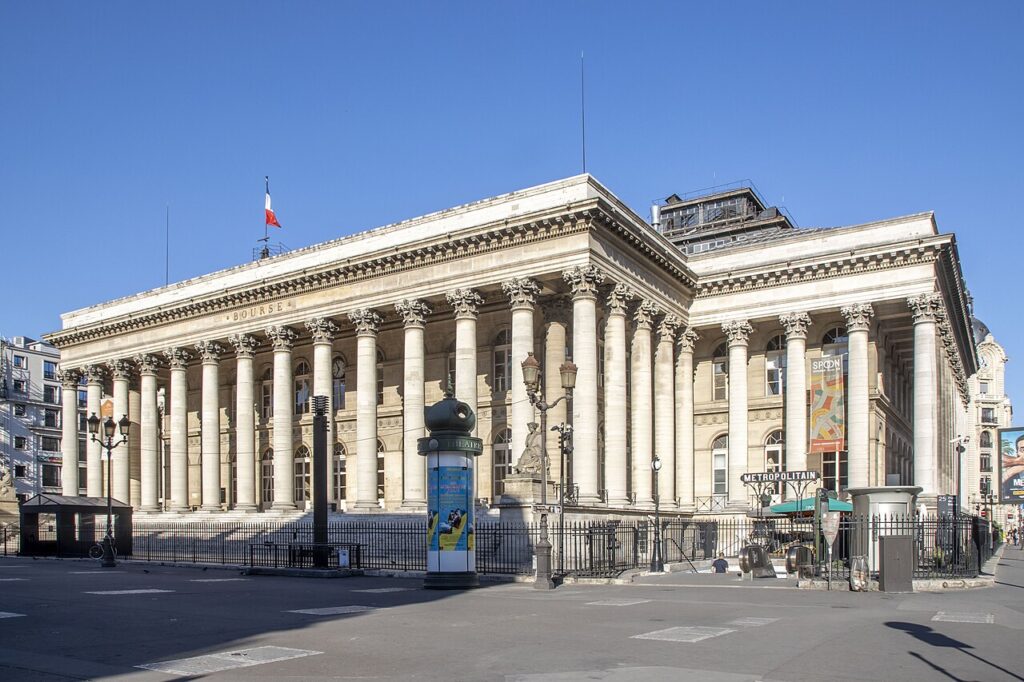
European equities extended their losses on Tuesday, and this time the selling had a specific address: France.
The Stoxx 600 — the benchmark index tracking 600 large European companies — fell 0.42% to 636.9. Germany’s DAX dropped 0.66% to 25,150. France’s CAC 40 slipped 0.31% to 7,845 (one snapshot put the decline at 0.7% to 7,811.65). Italy’s FTSE MIB lost 0.59% to 48,803, Spain’s IBEX 35 edged down 0.08%, and London’s FTSE 100 fell 0.28% to 10,734.
The bond market told the darker story. The yield on France’s 10-year government bond — the OAT — rose roughly 14 basis points (a basis point is one-hundredth of a percentage point) to around 4.93–4.94%, near its highest since July 2002. Germany’s 10-year Bund, the eurozone’s safety benchmark, sat near 3.43–3.44%. And the premium France pays over Germany — the OAT-Bund “spread” — stood at roughly 144 to 148 basis points on Tuesday. Monday’s 147-basis-point close was the widest since the 2012 eurozone sovereign-debt crisis (LSEG); Standard Chartered put Tuesday near 148. In late September the spread was around 110 basis points — a widening of roughly 37 basis points in a matter of weeks. For scale: during the 2011–12 crisis, the French spread approached 190 basis points. The euro, meanwhile, hovered near $1.12 — close to multi-month lows.
A credit story, not a protest story
Here is the point of view markets are now expressing: France is no longer being traded as a rich country with a protest problem. It is being priced as a credit story.
A spread does not widen 37 basis points in weeks on riot footage alone. It widens when investors look at the fiscal arithmetic and decide the government’s promises no longer add up. Eurostat puts France’s 2025 deficit at 5.1% of GDP, with public debt at 115.7% at end-2025 and a provisional 117.6% by end-Q1 2026. The enacted 2026 budget targets a 5.0% deficit; the European Commission’s May forecast projected 5.1% for 2026 and 5.7% for 2027. The question the spread is really asking: can a minority government push a credible 2027 budget through the National Assembly?
Analysts agree. Deutsche Bank’s Jim Reid called the unrest “another layer of political risk for markets,” Commerzbank’s Christoph Rieger warned of “signs of global, not just French debt crisis,” and Citi’s Jamie Searle: “Risk premium for French OATs is in uncharted territory… there is no obvious anchor level, and sentiment is in the driving seat.”
The real-economy damage
The unrest behind the numbers has been severe. Commerce Minister Serge Papin put the provisional toll at at least 3,000 shops damaged or looted. Prime Minister Sébastien Lecornu ordered prefects — the state’s top regional officials — to impose partial curfews; Place de la République and Les Halles in Paris were under overnight curfew October 19–20. Lecornu also announced 100% compensation through a partial-work program starting October 20, to protect jobs as businesses assess the wreckage.
More than 2,400 people were arrested over the weekend, and around 1,000 police officers were injured — the worst urban violence France has seen in years. Informopedia has been tracking the unrest as it unfolded: President Macron’s vow that rioters will pay after looters emptied luxury stores, and the interior minister’s admission that police lost control — and his offer to resign. Our companion explainer covers what a “spread” actually measures: what the OAT-Bund spread is and why markets watch it.
The tremors are crossing borders. In Italy, truck and semi-truck drivers began protesting rising fuel prices, blocking road and port entrances in southern regions — street-level anger at the cost of living is spreading beyond France. And across the Atlantic, the unrest has entered American politics: at a rally in Kansas on Monday, US President Donald Trump blamed “migrants, jihadists, and communists” for the French unrest.
What to watch
The spread’s verdict is unmistakable: investors doubt the fiscal path, and a 37-basis-point widening in weeks is the market betting against the 2027 budget. But the BlackRock Investment Institute’s caveat deserves weight: it calls the current situation “materially different” from 2011–12. The difference that matters: the European Central Bank now exists as a backstop — in 2011–12 it had to invent one mid-crisis. France is also still well short of the 190-basis-point panic levels of the last crisis.
Three things decide what happens next. First, Moody’s review of France’s credit rating — a downgrade would force the spread wider mechanically, as rating-sensitive funds rebalance. Second, the budget vote in the National Assembly — the spread is, at bottom, a bet on whether the minority government can legislate. Third, the streets: if the curfews hold and calm returns, some of the risk premium should bleed out. If not, the market will keep pricing France like the credit story it has become.