Paraguay’s Senate voted on Friday to remove President Santiago Peña from office, closing a four-day political crisis that began when a bank holding the savings of nearly half the country collapsed. Within hours, police had detained the former president at his home in Asunción, where he will stay under house arrest while prosecutors build a criminal case against him.
Forty-four of the Senate’s 45 members voted to convict Peña of misconduct in office. Vice President Pedro Alliana took the oath as president soon after the vote and will serve the rest of the term, which runs until August 2028.
Peña had tried to resign first. On Thursday he posted a video announcing his resignation, saying: “I have made the decision to submit my resignation from the Presidency of the Republic. I do so with the stability of our country, social peace, and the need to preserve our public institutions in mind.” Congress refused to accept it. The lower house had already voted 78-0 to press ahead with impeachment, and lawmakers wanted a conviction, not a resignation: a resignation would have left Peña with a lifetime Senate seat and the immunity that comes with it. Impeachment stripped both away.
His lawyers asked the Senate for 72 hours to prepare his defence. Senators rejected the request and went straight to the trial. Peña did not attend; his legal team represented him.
The Attorney General has opened three criminal cases against Peña and other former officials over the bank crisis, covering the supervision and winding-down of ueno, the placement of public money in the bank, and the actions of state authorities. Prosecutors cited suspected breach of trust when they ordered his arrest; further charges, including influence peddling and misappropriation of funds, remain possible.
Ueno was one of Paraguay’s biggest digital lenders, with about 2.9 million customers in a country of 6.1 million people. On Tuesday the central bank put the bank into resolution after finding its solvency ratio had fallen to 5.56 percent, less than half the 12 percent regulatory minimum. Accounts were frozen, and for two days customers queued outside branches, unable to reach their money.
Peña held shares in the holding company behind ueno until March 2025, and during his presidency public bodies — including the Social Security Institute, which manages most workers’ pensions — placed large sums with the bank. Peña has denied any direct relationship with the lender.
Not everyone in Congress wanted patience. “This guy, Santiago Peña, needs to be jailed. An arrest warrant must be issued … pretrial detention, straight to jail,” Senator Yolanda Paredes told reporters before the vote.
The central bank has begun processing guarantee payments to ueno customers in stages. Paraguay’s deposit guarantee covers up to roughly $38,000 per depositor, and the central bank estimates 97 percent of account holders fall entirely within that ceiling. Anything above it carries no guarantee of full recovery.
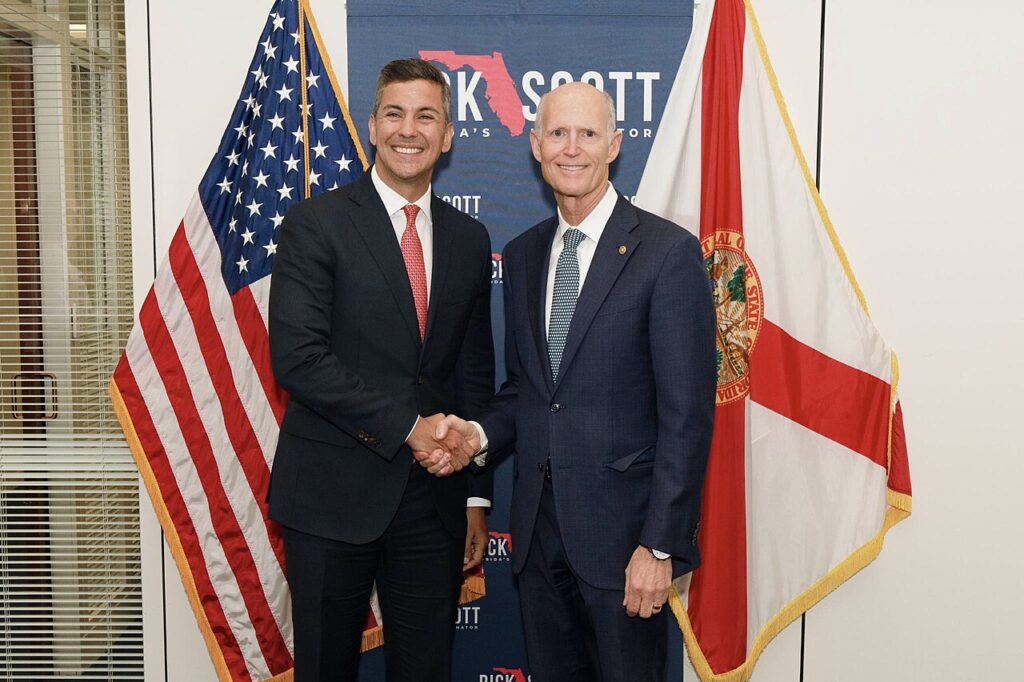
Peña was a close ally of the Trump administration in Washington, and the US State Department moved quickly to steady the relationship after his resignation, saying: “We remain committed to the enduring relationship between the American and Paraguayan people and look forward to continuing our close cooperation on shared priorities.” Alliana, for his part, reaches the presidency unencumbered: lawmakers had also weighed charges against him and rejected them, clearing his path to the top job.
Why this matters: A bank that serves half a country freezing its customers out is not a boardroom scandal. It is a shock to household budgets, pensions and small businesses, and it arrived in a country that had spent recent years pitching itself as a regional financial hub after winning investment-grade status from two major rating agencies. That pitch now sits beside images of queues outside frozen branches and a former president under house arrest. The impeachment also sets a marker: Peña is only the second Paraguayan president forced out by impeachment since 1989, and the first to face criminal detention on the same day. For the wider region, it is a reminder that the fastest-growing digital banks can also fail fastest — and that when they do, the political bill arrives within days, not years.